How longevity is moving from a demographic trend to a financial priority

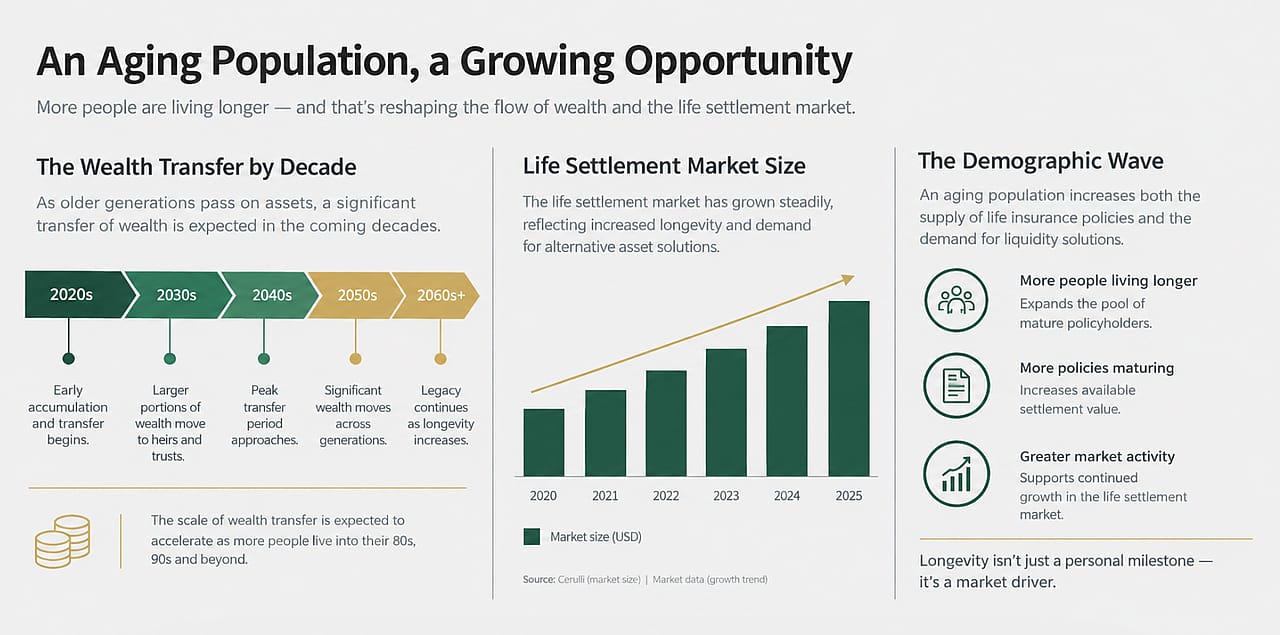
Life expectancy in the U.S. reached a new record length in the most recently published data, with the overall average age of 79, six months longer than the previous peak. Increased longevity brings practical challenges, and people must plan more thoroughly for the costs of living beyond the average.
There is also an element of uncertainty. While average life expectancies are useful for top-level calculations, they cannot account for the variables involved for individual people plotting out their retirement. Extended lifespans require personalized and thoughtful financial planning.
Retirement planning can become more complicated when actual career timelines differ from expectations. Many workers intend to stay employed well into their late sixties to maximize their Social Security benefits and employer matching contributions. The reality forces a different schedule entirely.
Recent data from the Society of Actuaries (SOA) reveals that 59% of retirees leave the workforce earlier than anticipated due to sudden caregiving obligations, health crises, or company downsizing. A premature exit halts the accumulation phase abruptly while simultaneously pulling forward the start of portfolio decumulation. When a person lives to be 95 but stops working at 61, the mathematical strain on their nest egg becomes severe.
Financial Shocks Before Retirement: A Hidden Threat
Pre-retirees are also facing unexpected hurdles before they even reach the finish line. The aforementioned SOA research found 29% of workers experience financial shocks that drain 10% or more of their accumulated savings right before they plan to retire. Recovering from a double-digit portfolio loss in a compressed timeframe requires careful structural planning.
According to Abacus Global Management, a life settlement company, establishing a personalized lifespan estimate turns longevity from a vague guess into a definitive input for a comprehensive wealth plan. Planners must build buffers that absorb early shocks without jeopardizing the fundamental structure of the income strategy.
Modern retirement models can address several core variables to prevent portfolio depletion. Specifically, they calculate the precise impact of inflation on purchasing power over three decades, segment assets into designated buckets for immediate income and long-term growth, and establish dynamic withdrawal rules that adjust to prevailing market conditions.
Why Average Lifespans Don’t Protect Your Retirement
The broader demographic trend of aging populations is forcing a collective rethink of what constitutes a safe withdrawal rate. The historical rule of 4% was designed for a 30-year retirement, but a healthy couple today will often see one partner survive well past the 35-year mark. Planning for an extended horizon requires more than just scaling up the initial savings target.
Longevity risk acts as a threat multiplier for every other financial hazard in retirement. If a portfolio suffers poor returns in the early years of withdrawal, the longer lifespan virtually guarantees that the principal will be exhausted prematurely. Investors who underestimate these longevity trends, which a Retirement Income Institute report analyzing data from the TIAA Institute and GFLEC suggests make up 53% of the population, are significantly less likely to save adequately, directly risking their financial independence.
Mitigating Sequence of Returns Risk
Sequence of returns risk means the order of investment returns matters as much as the average annualized return. A market downturn occurring in the first three years of retirement can heavily impact a portfolio, even if the subsequent decade produces massive gains.
Advisors can combat this by implementing a cash reserve or short-term bond ladder to cover immediate living expenses. This prevents clients from being forced to sell equities at a loss during a recession. By giving the portfolio’s growth engine time to recover, the total lifespan of the asset base is dramatically extended.
How Dynamic Withdrawal Strategies Work
The rigid nature of static withdrawal rates fails to accommodate the fluid reality of a long life. Taking a fixed percentage adjusted only for inflation ignores the underlying investments’ actual performance. In years where the market drops significantly, a static withdrawal forces the investor to sell an outsized portion of their shares to generate the same dollar amount.
Dynamic spending rules provide a mathematical solution to this problem. These strategies establish guardrails, stipulating that retirees should reduce their spending by a specific percentage if their portfolio drops below a certain threshold. Conversely, they allow for increased discretionary spending during periods of robust market growth.
Implementing a dynamic withdrawal strategy requires discipline and a willingness to adjust lifestyle expectations on the fly. However, the trade-off is a mathematically sound approach that drastically reduces the risk of portfolio ruin over a 40-year horizon.
Annuities as Longevity Insurance
Financial institutions are recognizing that longevity literacy is a glaring gap for the average consumer. Gallup research indicates that 55% of non-retirees worry about outliving their savings, making the fear of outlasting money greater than the fear of death for many still in employment. The industry is responding by developing new products designed specifically to provide guaranteed lifetime income.
Annuities are experiencing a renaissance as a tool for transferring longevity risk from the individual to an insurance company, with the category up 7% in 2025. Fixed indexed annuities and deferred income annuities offer a floor of guaranteed cash flow, which covers essential living expenses. The remainder of the portfolio can then be invested to outpace inflation and provide discretionary funds.
The Role of Long-Term Care Planning
Another critical component of an extended lifespan is the statistical probability of needing assisted living or in-home care. Many families discover too late that Medicare does not cover custodial care, such as assistance with bathing, dressing, or eating. Paying out of pocket for a private room in a nursing facility or hiring around-the-clock home health aides can drain hundreds of thousands of dollars in just a few short years.
Integrating long-term care insurance or hybrid life policies into the overarching financial plan protects the core portfolio from these steep medical expenses. While premiums require budget adjustments, these policies provide leverage that helps ensure an unexpected health crisis does not derail the surviving spouse’s future.
Adapting Portfolios for Extended Timelines
Addressing the realities of an aging society requires moving beyond outdated formulas and static averages. A robust financial strategy treats longevity not as an anomaly, but as the baseline expectation.
This story was produced by Abacus Global Management and reviewed and distributed by Stacker.
